Say you're facing surgeries and therapy that stretch years down the road, and the question you keep coming back to is who pays for all of it later. An injury like that doesn't stop costing money the day you sign a settlement. The bills keep coming for months or years afterward. A settlement that only counts what's already been spent leaves every one of those future bills on you. And so this is the piece of a serious claim that gets left on the table most often.
Future costs are economic damages too
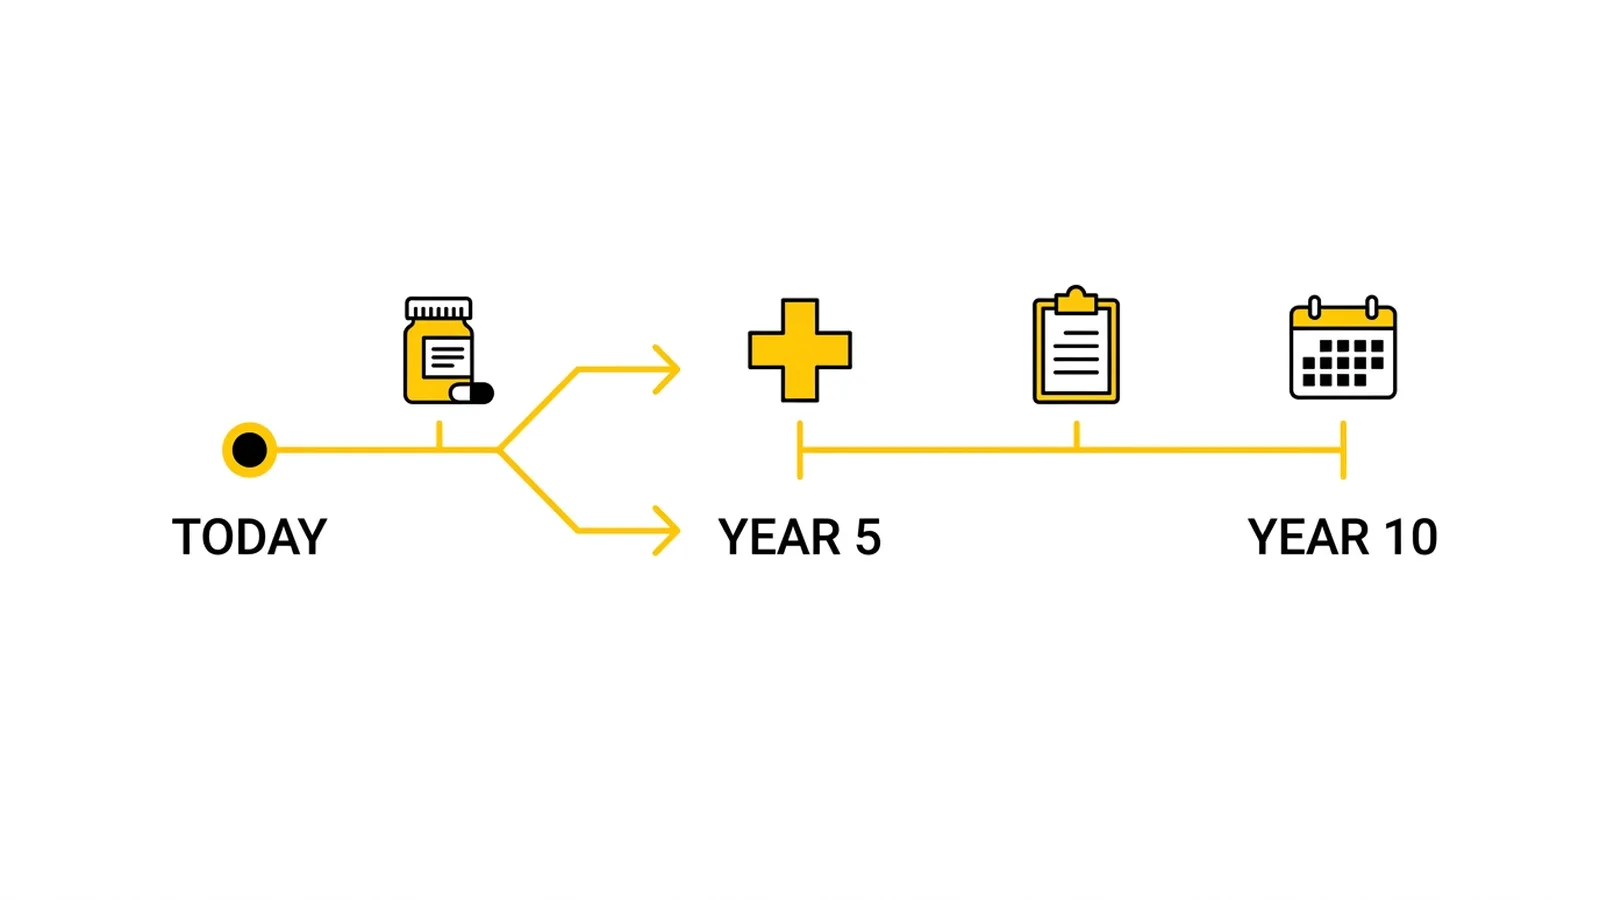
Future medical bills go into the damages figure right alongside the past ones. Future treatment is part of your economic damages, the hard, provable losses from Chapter 2, and those damages aren't limited to what has already happened. The difference is that future costs have to be projected, not added up from receipts in hand. So we use experts for that. A lot of times it's your own treating physicians. They project the cost and the duration of the care you're likely to need, and that goes into the medical records.
Access to the right specialists changes the projection itself
It's not enough to say it. Even when the injury plainly happened, we have to prove it through imaging and through specialists, and their opinions are what carry the demand. The same goes for care that hasn't happened yet. A specialist who treats your kind of injury every day produces a projection an adjuster finds much harder to dispute than one from a doctor working outside their lane. Think a neurologist for a head injury, or an orthopedic surgeon for a joint injury needing future surgery. That's part of why your choice of lawyer matters here. You may not know what specialist you need to see, but a good attorney will, because we've been there and done that. An attorney's access to the right specialists decides how completely future care gets captured in your settlement.
So the same way that we include the past medical bills, we include the future medical bills. So future treatment is a part of your economic damages calculation. It's not just limited to what's occurred.
One shot, permanently
The reason this chapter matters comes down to one hard fact. You get one shot. Once you sign a release, that claim is settled for good, with only very specific exceptions that I have not seen succeed in more than 13 years of practicing. If future care isn't in the number, that's a permanent loss the moment you sign. There's no second negotiation when new symptoms show up or a doctor recommends a surgery next year.
That's why rushing a settlement is dangerous for anyone with a serious injury. Sometimes these injuries take months and months to kind of reveal themselves. If you rush, you're not going to understand the full nature and extent of what you're dealing with. You'll have signed away the claim on care you'll eventually need.
The clock everyone is racing
There's a tension running under all of this. The advice not to rush runs up against the statute of limitations, the deadline Texas puts on bringing a claim, which Chapter 12 covers. You can't wait forever for an injury to show its full shape before the claim has to be filed. A treating physician can't always tell in month three whether a symptom is resolving or becoming permanent. So part of the work is predicting and projecting, through medical documentation, what you might have to spend in the future. Documentation is king here. Get care, keep it consistent, and build the record from the first visit. Then, when a real settlement decision has to be made, there's enough history behind it to project future costs with confidence instead of guessing under a deadline.
A treating physician who has followed your injury from week one is in a far better position to say, with confidence, what the next several years of care will look like. Better than a physician meeting you for the first time months in. None of that removes the pressure, and it shouldn't. It's a reminder that documenting thoroughly from the first appointment isn't just about proving what already happened. It's about protecting the ability to price what hasn't happened yet.
Beyond the accounting: what the right specialists change
This isn't only an accounting exercise. The physicians and specialists your case connects you with can be the difference between years of ongoing pain and something as simple as sitting comfortably again, or going for a walk without discomfort. A serious injury changes how you move and how you function, and future care is what gives you a shot at getting some of that back. When those costs are documented and funded, that's not a line on a spreadsheet. It's the difference between getting the surgery or the therapy your doctor recommended and skipping it because the money ran out once the case closed. That's the real stake behind an otherwise dry calculation.
What happens if the settlement doesn't fully cover future care
When a settlement comes in too low, or the future-cost projection wasn't built with enough medical support, the shortfall doesn't disappear. It lands on you the day the care is needed and the money isn't there. That's permanent. A signed release closes the door on going back for more once the real cost becomes clear. And so I'd rather push hard over a well-documented future-cost figure than take a faster settlement, because the first offer is never the best. A client who understands that trade-off up front is far less likely to feel blindsided later, when a projected surgery finally becomes necessary and the money isn't there.
Why the right attorney matters here specifically
Projecting future medical costs takes two things. Treating physicians and specialists who can put a documented number on care that hasn't happened yet, and a lawyer who knows how to turn that number into a properly supported damages figure. In a catastrophic case, a traumatic brain injury or a spinal cord injury that needs lifelong support, we go a step further and use a life care plan. Basically, an expert looks at every medical bill and record, maps out every future need and its cost, and projects it out against your life expectancy. You're not going to walk into every doctor's office and ask for an estimated bill for the next 25 years. That's what these experts are for, and it can add up to decades of damages. We get one shot at settlement and one shot at trial, so making sure we fully understand the picture of damages, using those experts, is a must. This is one of the clearest places in a claim where the quality of the records decides whether real money gets left on the table.
Common Questions
- Do future medical costs get included in a Texas crash settlement?
- Yes. Future treatment is part of your economic damages, projected forward through the medical records instead of added up from receipts. Your treating physicians, and where the case calls for it, retained experts, estimate what care you'll need and for how long, and that goes into the damages figure. Future costs aren't held out as a separate, speculative category. Leave them out and it's a permanent loss once you settle.
- Can I reopen my settlement later if I discover a worse injury?
- Usually not. Once you sign a release of liability or a settlement agreement, that claim is settled for good. There are some very specific exceptions, where you'd have to prove fraud by the insurer or the person who coaxed you into signing, and those are rare and hard to prove. So confirm the full spectrum of your injuries, including future treatment and its cost, before you sign. You get one shot.
- Why shouldn't I rush to settle my crash claim?
- Because some injuries, especially ones involving your back, neck, or brain, take months and months to reveal themselves. Settle before that picture is documented and you lock in a number that doesn't account for treatment you'll eventually need. A signed settlement is almost always permanent, so that gap can't be fixed afterward. The first offer is never the best, and if you rush it, you won't understand the full nature and extent of your injuries.
- Who decides how much future medical treatment I'll actually need?
- Your treating physicians, and where the case calls for it, retained experts such as a life care planner. They project the treatment you're likely to need and what it will cost, based on the documented injury and its expected course. That projection is what goes into the economic damages figure. It's a medical judgment translated into a claim, not a guess by the attorney.
- How far into the future do medical cost projections actually go?
- It depends on the injury and what the treating physician or specialist documents as reasonably likely. That might be a single surgery already recommended, physical therapy for a defined period, or lifelong care for a permanent condition. In a catastrophic case, a life care planner projects the cost out against your life expectancy, which can mean decades of damages. There's no default number of years. The projection follows the medical records, not a formula.
- Does a future medical cost projection need to come from a specialist, or can my regular doctor provide it?
- A regular doctor can provide it. But a specialist with direct experience treating your specific injury produces a projection an adjuster finds harder to dispute. A neurologist for a brain injury. An orthopedic surgeon for a joint that may need future surgery. The specialist's opinion carries serious weight with adjusters, and with a jury if the case goes that far. The credibility of the projection is often as important to the negotiation as the number itself.
Chapter Reflection
Future medical costs are the part of a claim I see left on the table most often. They haven't happened yet, so they're easy to overlook when there's pressure to close a case fast. Get the projection right, and get it into the record, before you sign anything. The next chapter turns to a different kind of forward-looking loss: what a crash costs you in your ability to earn a living, right away and for years afterward.